Why Your Health Insurance Should Not Lower What a Negligent Driver Owes You
Key Takeaways: Virginia’s collateral source rule is a common-law doctrine holding that a negligent defendant must fully compensate an injured person regardless of whether health insurance, MedPay, workers’ compensation, or other benefits paid first. It operates as an evidentiary rule barring juries from hearing about outside payments and as a damages rule preventing recovery reductions. Virginia courts reason that any “windfall” should go to the injured victim rather than the wrongdoer, as reflected in Acuar v. Letourneau, which addressed amounts written off by providers under insurer agreements. Because Virginia has not adopted a phantom damages statute, plaintiffs may generally present full billed amounts, subject to proof of reasonableness, necessity, and causation. Va. Code § 8.01-243 requires personal injury suits within two years of accrual.
If you were hurt in McLean and your health insurance, MedPay, or employer benefits paid medical bills, the at-fault party generally gets no discount for that help. That principle is the collateral source rule, a long-standing common-law doctrine in Virginia holding that a negligent defendant must fully compensate the person they injured regardless of whether insurance, family, or an employer stepped in first. Benefits you or your family arranged are treated as your benefit, not a credit the wrongdoer claims, though separate lien, subrogation, or reimbursement obligations may still apply.
If an adjuster argues that your recovery should shrink because insurance already paid, you may want a case-specific review before accepting any offer. The plaintiff-focused team at Tysons Trial Law, PLLC handles injury matters throughout Fairfax County and can explain how the collateral source rule may apply to your damages. Call (703) 888-5535 or schedule your consultation now to discuss your options.
The Core Idea Behind the Collateral Source Rule Virginia Courts Apply
Virginia’s Supreme Court has framed the doctrine around a simple fairness judgment: if anyone receives a “windfall,” it should be the victim rather than the wrongdoer. That reasoning appears in Acuar v. Letourneau, 260 Va. 180 (2000), where the Court held that amounts written off by health care providers pursuant to agreements with the plaintiff’s insurer remained recoverable as part of the reasonable value of medical services. The logic is that a defendant who caused harm should not benefit from the foresight, premiums, or generosity of someone else.
The doctrine descends from inherited English common law and has been recognized in American decisions since at least the mid-nineteenth century. Because it is judge-made law rather than statute, its contours develop through appellate decisions.
Two Functions in One Doctrine
The rule operates in two ways in a Virginia injury claim. First, as an evidentiary rule: evidence that your insurer paid your bills is generally inadmissible at trial, subject to the trial court’s discretion and exceptions such as impeachment. Second, as a damages rule: your recovery is generally not reduced simply because a collateral source already paid.
These functions matter at different stages. The evidentiary side relates to what a jury may hear. The damages side relates to the math on the verdict form.
Who Counts as a “Collateral Source”
A collateral source is a payer whose obligation to you exists independently of the at-fault party’s wrongdoing. Courts and commentators commonly include:
Your own health insurance plan
Workers’ compensation benefits
MedPay coverage under an auto policy
Employer-provided sick leave or disability pay
Gratuitous care or financial help from family and friends
Workers’ compensation deserves particular care because Virginia’s Workers’ Compensation Act gives the employer or its carrier statutory lien and subrogation rights against a third-party recovery.
How the Rule Affects Medical Bills in a McLean Personal Injury Case
The most common battleground is the difference between the amount billed and the amount actually paid. Many states have adopted “phantom damages” reforms limiting proof of past medical expenses to amounts actually paid. Virginia has not adopted such statutory limitation, so injured plaintiffs may present the full billed amounts, subject to ordinary evidentiary requirements that charges be reasonable, necessary, and causally related.
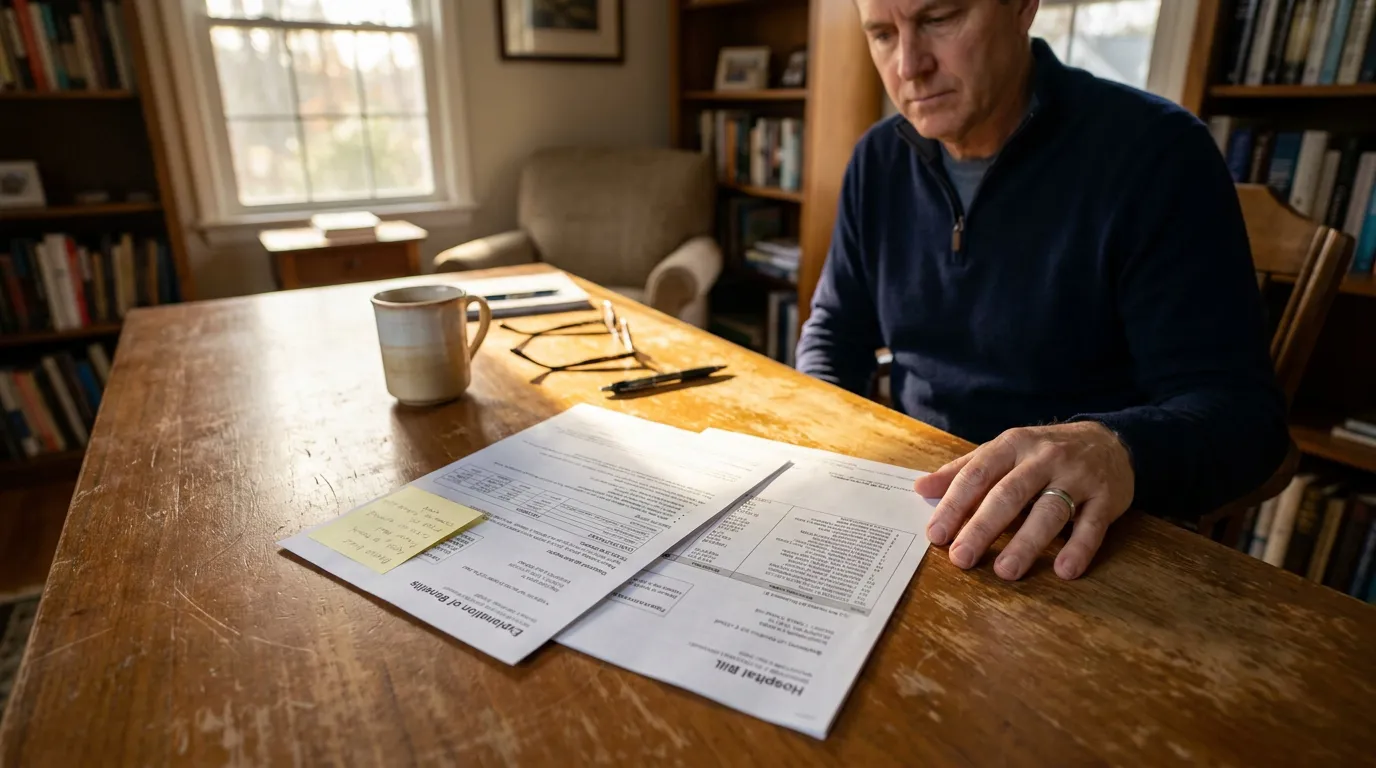
That distinction can be worth a great deal in serious cases. A hospital may bill a substantial sum while a health insurer pays a negotiated fraction. Whether the larger figure reaches the jury is often the most contested damages question in a Virginia injury claim.
💡 Pro Tip: Request itemized statements and explanation-of-benefits forms from every payer early. Reconstructing billing records months later is far harder than collecting them as they arrive.
Statutes That Interact With the Doctrine
Two Virginia insurance statutes shape how medical payments work, though neither codifies the collateral source doctrine itself. Under Va. Code § 38.2-2201(A), insurers issuing motor vehicle liability policies in Virginia must offer minimum coverage for reasonable and necessary medical, hospital, surgical, and rehabilitation expenses incurred within three years of an accident, in an amount of at least $2,000 per person. That statute addresses when an expense is “deemed incurred,” including situations where a health care insurer, Medicaid, or Medicare pays a negotiated amount.
Va. Code § 38.2-2211 addresses overlapping medical expense coverage. It prohibits a motor vehicle liability policy from crediting other medical expense insurance against its own medical expense coverage, while providing that nothing allows an injured person to collect more than actual medical expenses from any one policy or combination of motor vehicle medical payment policies. Reading the Virginia medical expense coverage statute alongside the common-law doctrine helps clarify a frequent point of confusion: the collateral source rule governs what a jury may hear about outside payments in a tort case, while this statute is a first-party insurance provision addressing limits on recovery among overlapping auto medical payment policies.
Concept | Source of Law | What It Governs |
|---|---|---|
Collateral source rule | Virginia common law | Admissibility of outside payments and reduction of damages |
Va. Code § 38.2-2201(A) | Statute | Minimum medical/disability benefits; when an expense is “deemed incurred” |
Va. Code § 38.2-2211 | Statute | Anti-credit provision and cap on stacking auto medical payment coverage |
Va. Code § 8.01-243 | Statute | Filing deadline for personal injury and property damage actions |
Many readers find it helpful to review how MedPay compares to health insurance before deciding which policy to submit bills to first.
Where the Collateral Source Doctrine Remains Unsettled
Virginia’s application of the rule is not entirely settled at the margins. A footnote in Schickling v. Aspinall, 235 Va. 472 (1988), questioned whether the doctrine’s rationale holds where the plaintiff’s own insurer has subrogation rights and the defendant is also insured. The suggestion was that the usual justification is “arguably” weakened in that posture, though the observation was dicta rather than a holding, and later decisions such as Acuar have continued to apply the traditional rule.
That open question carries real weight because subrogation is common. Many insurers have subrogation rights, meaning they may be entitled to reimbursement from the insured’s recovery. If a subrogation-based exception were broadly recognized, it could touch a large share of injury claims.
The Policy Debate You Will Hear From Insurers
Tort reform organizations have argued for years that the doctrine should be narrowed or abolished. Their position is that collateral source payments should either be admissible at trial or offset against awards, while defenders respond that subrogation and lien rights often eliminate any true double recovery.
Deadlines Still Control Everything
Even the strongest damages argument may fail if the claim is filed late. Under Va. Code § 8.01-243(A), every action for personal injuries must be brought within two years after the cause of action accrues. Subsection (B) provides a five-year period for injury to property, and the statute contains provisions for certain medical malpractice actions. Other statutes set different deadlines in particular circumstances, including wrongful death actions and claims against governmental entities, which carry separate notice requirements.
Exceptions such as tolling or delayed accrual exist in limited circumstances, and Virginia courts generally construe them narrowly.
Frequently Asked Questions
1. Will the jury be told that my health insurance paid my hospital bills?
Generally, no. The collateral source rule typically bars admission of such payments. Trial courts retain discretion over evidentiary disputes, and specific facts can occasionally open the door.
2. Does the rule mean I keep both the insurance payment and the verdict?
Not necessarily. Your insurer may hold subrogation or lien rights entitling it to reimbursement from your recovery. Health plans, MedPay carriers, ERISA plans, and government payers such as Medicare and Medicaid have differing rights. The rule may limit what the defendant argues but does not eliminate your reimbursement obligations.
3. Can I recover the full billed amount of my medical bills?
Virginia has not enacted a phantom damages statute limiting proof to amounts actually paid, so plaintiffs may present billed amounts. You must still show the charges were reasonable, necessary, and causally related. Outcomes depend on the medical evidence and trial court’s evidentiary rulings.
4. Does the collateral source rule apply outside of car crash cases?
The doctrine is a general principle of Virginia tort law and is not limited to auto collisions. It has been discussed in product liability and other tort contexts. Application depends on specific facts and procedural posture.
5. What if a family member paid my bills instead of an insurer?
Gratuitous assistance is generally treated as a collateral benefit, meaning the wrongdoer typically receives no credit. Documentation of the services or payments provided, and evidence of their reasonable value, still matters.
Protecting the Full Value of Your Damages
Virginia’s collateral source rule reflects a deliberate choice: benefits you secured through premiums, employment, or family support should not reduce what a negligent party owes. It functions both as an evidentiary shield and as a damages rule, and it interacts with statutes like Va. Code §§ 38.2-2201, 38.2-2211, and 8.01-243. The doctrine has unsettled edges, particularly around subrogation, so results depend on specific facts and evidence developed.
If an insurer is discounting your claim because someone else paid first, a prompt review can help you understand what Virginia law may permit you to recover. Contact Tysons Trial Law, PLLC at (703) 888-5535, visit the firm’s McLean injury team, or request a case review today to talk through your injury settlement in Virginia.
Disclaimer: This content is for informational purposes only and is not legal advice. Every case is unique, and results may vary. Consult an attorney about your specific circumstances.